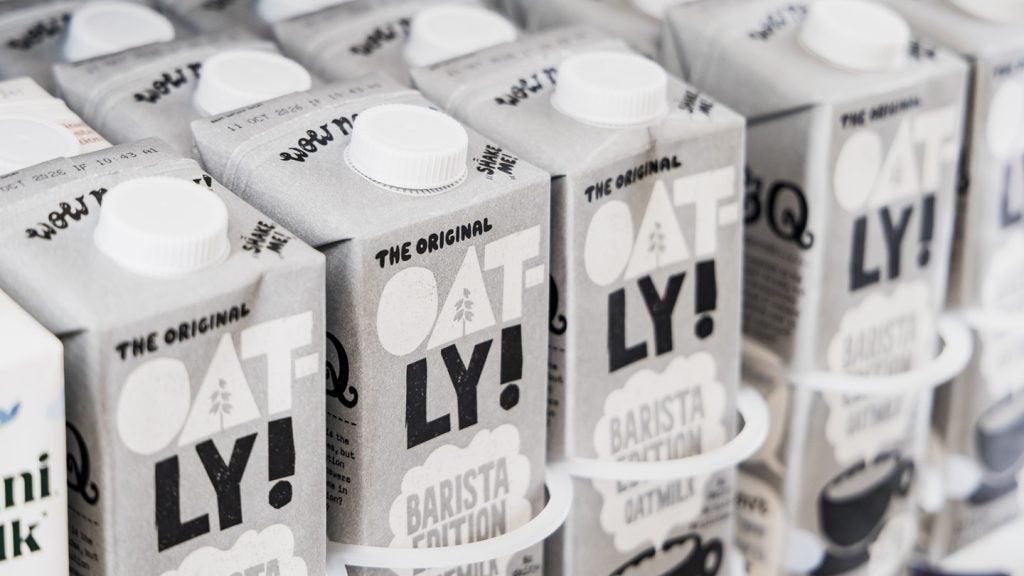
Oatly has lowered its full-year profit guidance due to soaring fuel and freight costs in North America, even as third-quarter net losses narrowed.
The Sweden-headquartered oat-drinks maker now expects adjusted EBITDA of $16m to $20m, down from its previous projection of $25m to $35m.
For the downgrade, CEO Jean-Christophe Flatin cited the “latest wave of fuel and freight inflation in North America which has been stronger and faster than expected”.
In prepared remarks before yesterday’s (28 October) earnings call, Flatin outlined the roughly 70% surge in US diesel prices since the onset of the Middle East conflict in February, and a 40% increase since early July.
“We possess multiple levers to offset this pressure, but timing delays will adversely impact our profit in the fourth quarter,” he added.
However, the company maintained its constant-currency revenue growth forecast at 8% to 10%.
It also reaffirmed expectations of currency movements adding around 200 to 250 basis points to reported revenue growth, with capital expenditure still projected at $20m to $30m.
The outlook downgrade comes despite growth in the third quarter.
The group’s revenue for the three months to 30 September rose 9.1% year-on-year to $243.1m, representing 8.9% growth in constant-currency terms.
Gross margin expanded by 4.4 percentage points to 34.1%, while total volumes increased 4.2% to 156.9 million litres.
Net losses attributable to the parent shareholders narrowed to $27.5m from $65.3m a year earlier. Adjusted EBITDA reached $9.4m, compared to $3.1m in the prior-year quarter.
Greater China was the only segment to report weaker sales, with revenue slipping 14.6% to $32m, or 19.3% to $30.2m excluding a $1.8m foreign-exchange benefit. Foodservice competition drove the decline, partly offset by higher retail sales.
The segment swung to an adjusted EBITDA loss of $1.9m in the quarter, from a profit of $1.6m in the prior year, amid lower volumes and higher selling expenses.
Conversely, North America returned to positive adjusted EBITDA of $0.3m, against a $1.3m loss a year ago. Revenue for the business increased 2.8% to $63.8m, while volumes edged up 0.4% to 34.6 million litres.
Europe and International revenue climbed 19.5% to $147.2m, driven by 17.6% volume growth, particularly in Barista products. Adjusted EBITDA increased to $31.5m from $21.9m.
Oatly is still in the midst of a “strategic review” of its Greater China business, weighing a “range of options including a potential carve-out”. The review is expected to be completed this year.